Project Agorá Tests 80-Second Cross-Border Settlement Using Tokenised Deposits and Central Bank Reserves
Oct. 29, 2026 • Deep Dive • Digital Assets
Project Agorá’s real-value testing settled 30 live, multi-currency transactions worth approximately CHF 800,000, with atomic settlement averaging about 80 seconds. The tests involved 28 commercial institutions and five central banks. The result shows how tokenised commercial bank deposits and central bank reserves could support faster cross-border settlement, though it does not establish that settlement latency has been eliminated.
The project’s prototype found that tokenisation did not change the legal character or regulatory obligations of deposits and reserves. Its design also let participating institutions conduct compliance checks concurrently. Seven more commercial banks joined in September 2026, taking private-sector participation to nearly 50 institutions. At Sibos in October, banking executives described the testing pipeline as a step towards production trials alongside the European Central Bank’s Pontes platform. The Federal Reserve Bank of New York did not participate in the live test transactions, an important qualification for the US dollar tests.
Project Agorá’s live testing settled 30 multi-currency transactions in an average of approximately 80 seconds, offering evidence that tokenised commercial bank deposits and central bank reserves can support faster cross-border settlement. The transactions, worth about CHF 800,000 in total, involved 28 commercial institutions and five central banks.
The results address a question for banks considering tokenised money: whether they can change how payments move without changing what a deposit is. The project’s prototype found that tokenisation did not alter the underlying legal character or regulatory obligations of commercial bank deposits and central bank reserves. That finding supports the design’s compatibility with existing banking obligations, but it does not, by itself, establish every operational consequence for fractional-reserve banking.
What the live tests showed
Project Agorá’s real-value testing used multi-currency atomic settlement: the linked parts of a transaction settle together rather than leaving one completed while another remains outstanding. The reported average of roughly 80 seconds describes the transactions tested. It is not a claim that cross-border settlement latency has been eliminated, nor does the research package provide a conventional-payment benchmark against which to measure the result.
The prototype used a two-layer architecture for tokenised commercial bank deposits and central bank reserves. Kaleido designed and deployed the distributed-ledger architecture for both the prototype and real-value testing phases, while SIX acted as operational facilitator. The distinction between the two forms of money matters: tokenising a bank deposit did not turn it into a central bank reserve or remove its existing regulatory obligations.
Project Agorá also implemented programmable smart contracts so participating institutions could run anti-money-laundering, counter-terrorist-financing and sanctions checks concurrently rather than sequentially. This tests whether compliance work can proceed alongside other steps in a cross-border transaction, without dispensing with those checks.
Participation and the limits of the result
On September 29, 2026, Barclays, BMO, CIBC, Rabobank, RBC, Scotiabank and Wells Fargo formally joined Project Agorá. Their addition expanded private-sector participation to nearly 50 institutions. The broader project’s central bank participation also changed over time: early accounts referred to seven central bank jurisdictions, while the Bank of Canada joined in May 2026 as an eighth central bank participant.
Those broader participation figures should not be confused with the scope of the live transactions, which involved five central banks. The Federal Reserve Bank of New York took part in the initial design and prototype validation but did not participate in the July 2026 real-money transactions. US dollar transactions in that test therefore took place without direct central bank settlement participation. That qualification is important when interpreting what the multi-currency results demonstrate.
The scale of cross-border payments explains the interest in the work. Wholesale flows accounted for roughly 91% of total global cross-border payments value, which reached $195 trillion in 2024 and is projected to reach $320 trillion by 2032. Faster processing and coordinated settlement could matter across a market of that size, but the project’s 30 transactions remain a test rather than a measure of performance across wholesale payments generally.
Why the deposit structure matters
The Bank for International Settlements’ concept of a unified programmable ledger aims to preserve the “singleness of money”: different forms of money exchange at par, with settlement finality anchored in central bank reserves. In Project Agorá, the prototype’s legal finding is therefore as significant as its settlement timing. It indicates that the technology can represent deposits and reserves on a new infrastructure without redefining their legal status.
That is narrower than proving that tokenised deposits resolve every question raised by fractional-reserve banking. The reported tests establish a legal and technical design, alongside a limited set of live payments. They do not provide findings on banks’ lending, liquidity management or performance at production scale. The supported conclusion is that tokenisation need not change a deposit’s existing obligations simply to enable a different settlement process.
At Sibos 2026 on October 29, international banking executives said Project Agorá’s real-value testing pipeline was paving the way for next-phase production trials alongside the European Central Bank’s Pontes platform. Production trials remain a next step, not an outcome of the transactions reported so far. The tests show that faster, coordinated multi-currency settlement is possible within the project’s design; they stop short of showing that cross-border latency can be eliminated.
Project Agorá’s real-value testing settled 30 live, multi-currency transactions worth approximately CHF 800,000, with atomic settlement averaging about 80 seconds. The tests involved 28 commercial institutions and five central banks. The result shows how tokenised commercial bank deposits and central bank reserves could support faster cross-border settlement, though it does not establish that settlement latency has been eliminated. The project’s prototype found that tokenisation did not change the legal character or regulatory obligations of deposits and reserves. Its design also let participating institutions conduct compliance checks concurrently. Seven more commercial banks joined in September 2026, taking private-sector participation to nearly 50 institutions. At Sibos in October, banking executives described the testing pipeline as a step towards production trials alongside the European Central Bank’s Pontes platform. The Federal Reserve Bank of New York did not participate in the live test transactions, an important qualification for the US dollar tests.
Ripple’s final federal trust bank charter, a Moody’s investment-grade rating for RLUSD and a planned expansion of the stablecoin’s availability on Coinbase have strengthened its position as a regulated digital dollar. Coinbase said Global Exchange access, including eligibility to use RLUSD as trading collateral, will follow its initial retail and prime rollout. Moody’s assigned RLUSD an A2 long-term deposit rating and a P-1 short-term rating, the first investment-grade rating it has given a stablecoin. The distinctions behind those developments matter. Ripple National Trust Bank manages RLUSD’s reserve collateral, but the legal issuer remains Standard Custody & Trust Company, a New York-regulated Ripple subsidiary. The national trust bank is uninsured and cannot take commercial retail deposits or extend credit. Moody’s also noted that holders do not currently own the underlying reserves directly and that statutory bankruptcy protections depend on implementation of the GENIUS Act, whose rules take effect in January 2027.
Ramp partnered with Stripe and Bridge in July 2026 to deploy stablecoin rails for business bill payments and yield-bearing stablecoin accounts funded through standard fiat bank accounts. The arrangement shows how stablecoins can be incorporated into familiar payment workflows without requiring businesses to fund every transaction with digital assets. The economics depend on more than the cost of moving a token on-chain. Stripe charges merchants 1.5% for stablecoin checkout transactions, versus its standard card-processing fee of 2.9% plus $0.30; neither figure establishes the price of Ramp’s bill-payment service. Businesses receiving fiat may also face foreign-exchange and off-ramp costs, typically 0.3% to 2.0% when converting into local banking systems. Domestic clearing networks and compliance checks remain part of end-to-end delivery. Bridge’s issuance and transfer tools, alongside its conditional U.S. trust-bank approval, illustrate the infrastructure behind those payments—but not the elimination of every payment cost.
StraitsX has opened onboarding for digital payment token providers across more than 100 markets through an expanded card-issuing architecture developed with Visa. Integration documentation published on 26 October 2026 describes a multi-BIN model that combines issuing sponsorship, transaction authorization, compliance screening and fiat clearing. The approach lets participating providers build stablecoin-backed card products while merchants continue to receive conventional fiat payments through Visa’s network. StraitsX says its card gross transaction value rose 40-fold year on year from Q4 2024 to Q4 2025, while cards issued across Asia increased 83-fold. On-chain issuer telemetry recorded monthly card transaction volume of $310 million to $438 million through October 2026. The company’s stated $6 billion annualized card transaction figure is distinct from its cumulative $70 billion in processed stablecoin volume. StraitsX and Visa have also scheduled demonstrations of agentic payments for November 2026.
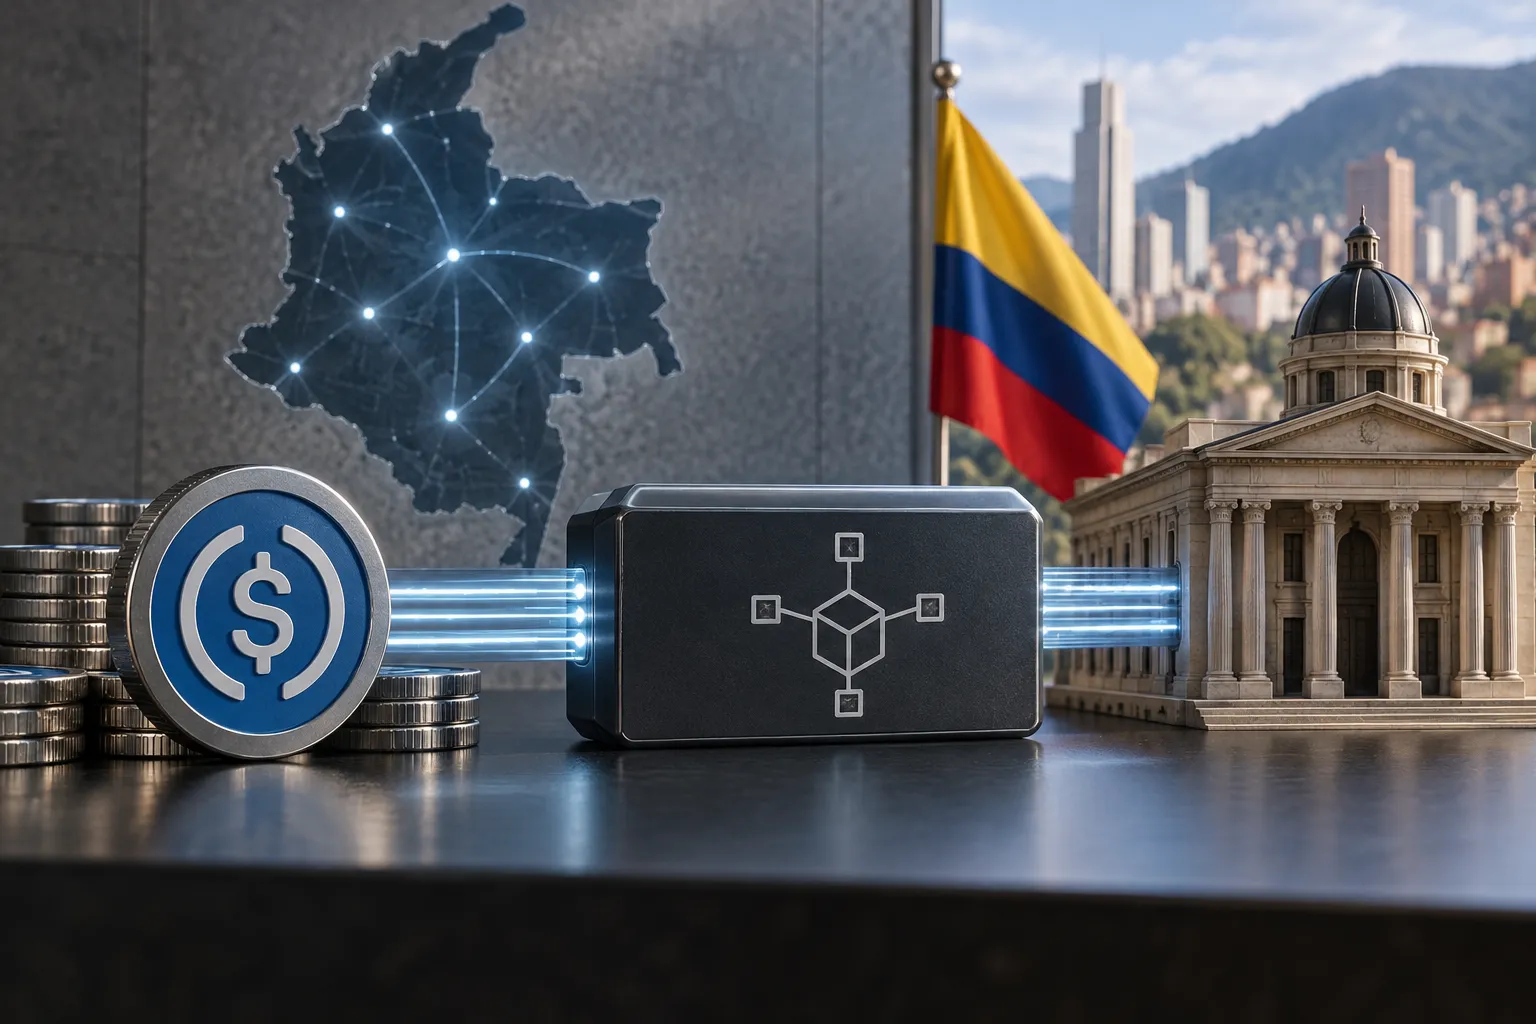
ACI Worldwide and Circle announced a pilot on October 27, 2026, involving USDC and connectivity to Colombia’s Bre-B instant payments system. The integration runs through ACI Connetic, a payments orchestration platform, rather than embedding USDC in Bre-B’s central infrastructure. There is no indication that Colombia’s central bank has adopted USDC as a settlement asset for the national network. The distinction matters because ACI also supplies technology for Bre-B’s central directory and real-time clearing engine. Bre-B launched in October 2025 and handled more than 500 million transactions within five months. Connetic is designed to bring traditional payment rails and digital asset networks together without requiring banks to replace legacy core ledgers. ACI says the platform can support other digital assets and liquidity providers, so the pilot does not make USDC its exclusive option. The arrangement tests a vendor-level connection alongside an established public payment system, not a change to that system’s settlement rules.
Ripple received final approval on 26 October 2026 for Ripple National Trust Bank, giving it a federally chartered institution for fiduciary and custody activities. The charter does not authorize commercial deposits or loans, and it does not transfer issuance of Ripple’s RLUSD stablecoin to the new bank. RLUSD issuance remains with Standard Custody & Trust Company under New York State Department of Financial Services supervision. BNY is the primary custodian of the dollar deposits and U.S. Treasury reserves backing the stablecoin. The arrangement separates a federal custody role from state-supervised issuance. It also comes as the OCC implements the GENIUS Act’s stablecoin rules and faces a lawsuit from the Independent Community Bankers of America challenging its authority to grant national trust charters to crypto firms. Ripple has separately announced an expanded partnership with BNY and Robinhood focused on institutional custody capabilities and exploring tokenized trade finance.