Mastercard opened developer early access for Agent Pay for Machines (AP4M) on October 20, 2026, releasing buyer- and seller-side APIs, a sandbox and developer toolkits. In a Cloudflare Connect demonstration, marketing agency Hype tested an autonomous agent making nine payments to two merchants within a single budget, without manual billing or account setup. AP4M uses HTTP 402 payment challenges, but differs from crypto-native implementations of the x402 protocol. Its agents issue digitally signed vouchers off-chain; merchants can batch and redeem them later instead of settling every request on-chain. The pilot combined agent wallet infrastructure from Coinbase Developer Platform and BVNK, settlement on Base, and Mastercard’s multi-currency fiat and stablecoin settlement platform. Circle separately expanded its managed payments service to target AI-agent traffic using USDC. Together, the developments show competing approaches to machine-to-machine payments, with different choices about settlement, funding and who manages digital assets.
Sumitomo Mitsui Banking Corporation (SMBC) and Ant International signed a memorandum of understanding on October 26, 2026, to explore cross-border payments and digital treasury services. Their initial focus is Japan, Singapore and wider Southeast Asia. Engineering teams will examine whether Ant International’s Whale RTP platform can be integrated with SMBC’s institutional transaction banking and digital asset platforms. The agreement is exploratory, not the launch of a live settlement service. SMBC’s multi-market transaction banking rails are expected to support operations involving Ant International’s Alipay+, Antom and WorldFirst businesses. Ant International says its Whale platform processed more than US$600 billion in global treasury flows in 2025, with over 95% of transactions settling on the same day. Those figures describe the existing platform, not activity under the SMBC agreement. The MoU follows separate tokenized-deposit work involving Ant International and other banks, including a live OCBC solution and an HSBC pilot.
Tech Mahindra and Finastra announced on October 23, 2026, that Tech Mahindra had completed its acquisition of Finastra’s cash management products and related intellectual property. The deal moves Tech Mahindra beyond implementing banking software for clients and into owning transaction banking products. Financial terms were not disclosed. The acquired portfolio includes Fusion Cash Management, Fusion Virtual Accounts and Fusion Liquidity Management, along with CashPlus, Global CashPlus and associated transaction banking APIs. Finastra product engineering and customer success personnel are being moved into Tech Mahindra’s banking, financial services and insurance division. Tech Mahindra plans to integrate the products into its existing Finastra Centre of Excellence to maintain service continuity for banking clients. The acquisition follows Tech Mahindra’s earlier purchase of an 85% stake in Canadian fintech Avant Techno Solutions and comes as Finastra divests businesses to concentrate on lending and payments software.
Fireblocks has rejected an Axios report that Visa was in advanced talks to acquire the digital-asset infrastructure company for about $2.5 billion. Fireblocks said the reported discussions were not taking place at present. Visa declined to comment on the claim, while Coinbase separately denied reports that it was considering a bid. None of the companies has confirmed an acquisition process. The reported price would be about 69% below Fireblocks’ $8 billion valuation from its January 2022 Series E funding round. The company generated $124 million in revenue in 2024 but remained unprofitable, and it has initiated plans to cut 60 to 70 jobs amid the rumors. Visa already uses Fireblocks as an institutional client and works with it on an interoperability initiative. Those existing links provide context for the speculation, but do not establish that a transaction is under discussion.
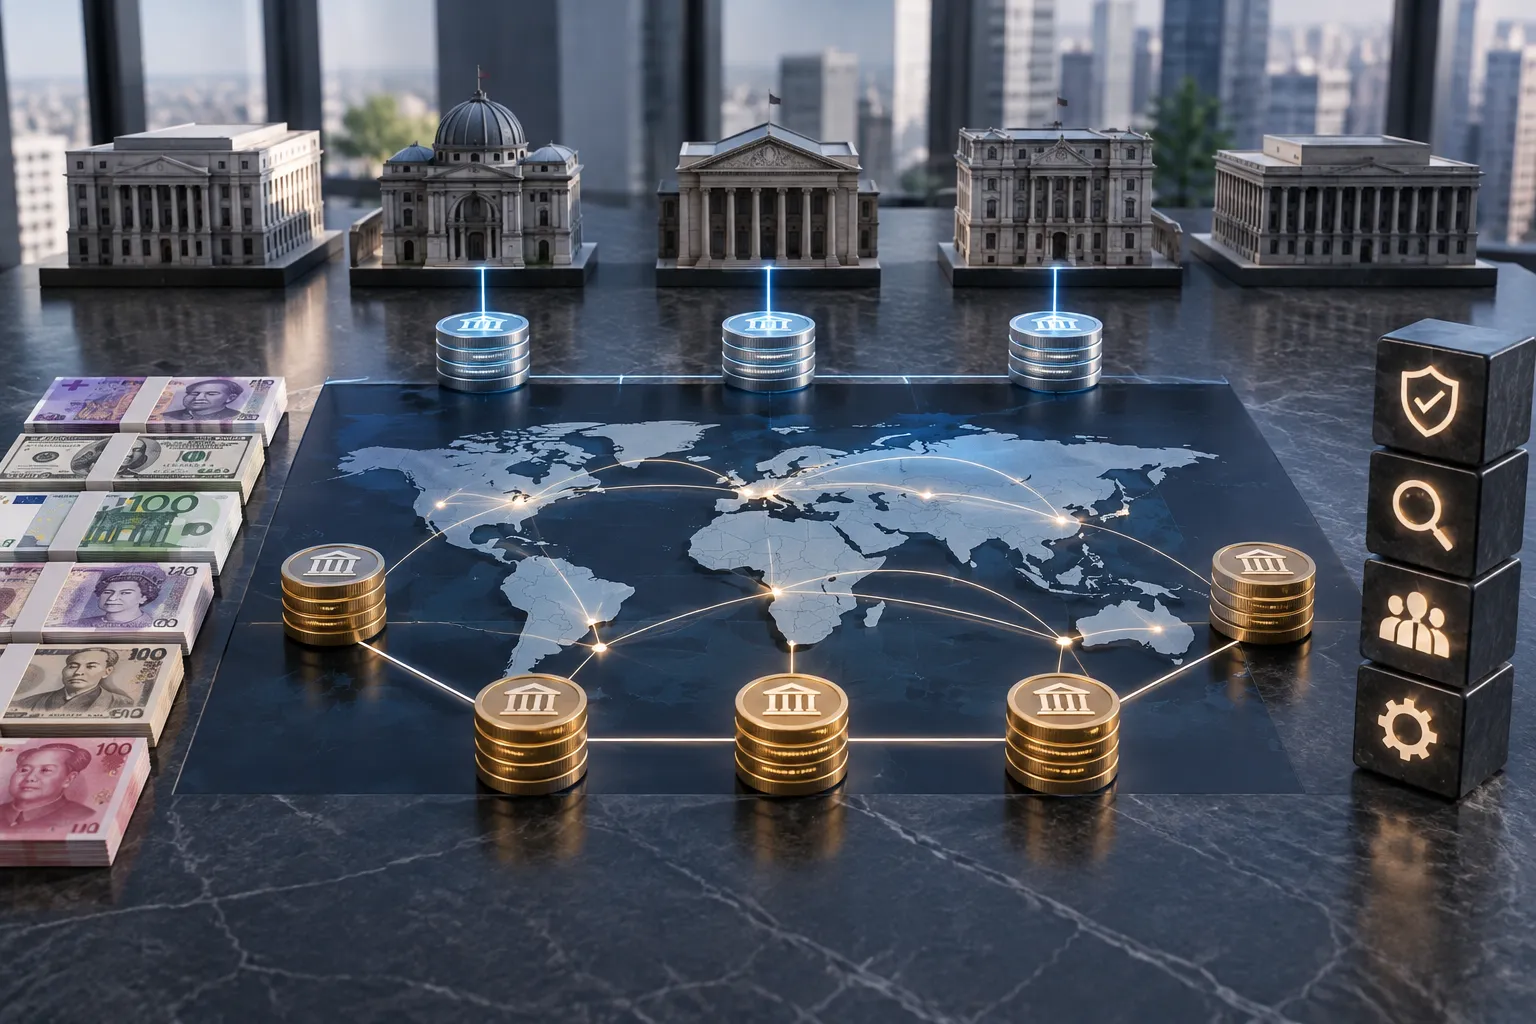
Project Agorá settled approximately CHF 800,000 in live, multi-currency transactions during a July 2026 testing phase. The work examined a cross-border payment model that places tokenised commercial bank deposits on a shared ledger while holding tokenised central bank reserves on jurisdictional ledgers. Five central banks participated directly in live-reserve settlement, although the project’s wider central-bank group has since expanded to eight with the Bank of Canada’s entry. The project reports an average settlement time of 80 seconds across six currencies and uses smart contracts to run anti-money laundering, sanctions and fraud checks simultaneously. Legal analyses found that tokenisation did not change the underlying character of deposits or reserves in participating jurisdictions. The findings support further work on deposit-based wholesale settlement, but the supplied research does not establish that the approach outperforms stablecoins. The Eurosystem plans to draw on Agorá’s architecture for Projects Pontes and Appia.
The Monetary Authority of Singapore has issued tokenised MAS Bills in live trials on its Singapore Dollar Test Network, settling them with wholesale central bank digital currency. An initial S$1 million one-week tranche was followed by a S$10 million tranche scheduled to mature on October 23, 2026. MAS says placing tokenised securities and central bank money on common infrastructure supports monetary stability and settlement finality. Separately, the Bank for International Settlements and the Institute of International Finance completed real-value testing for Project Agorá. Twenty-eight financial institutions and five central banks executed 30 transactions worth CHF 800,000 across six currencies, averaging 80 seconds per settlement. The initiatives illustrate why central banks favour wholesale CBDCs and tokenised bank deposits for institutional transactions: they aim to preserve settlement in central bank money and the existing banking system. Stablecoins remain a competing model, with industry participants citing their liquidity and round-the-clock availability.