Central banks test atomic FX settlement across separate RTGS and DLT systems without unified ledger
Nov. 16, 2026 • Article • Banking & Payments
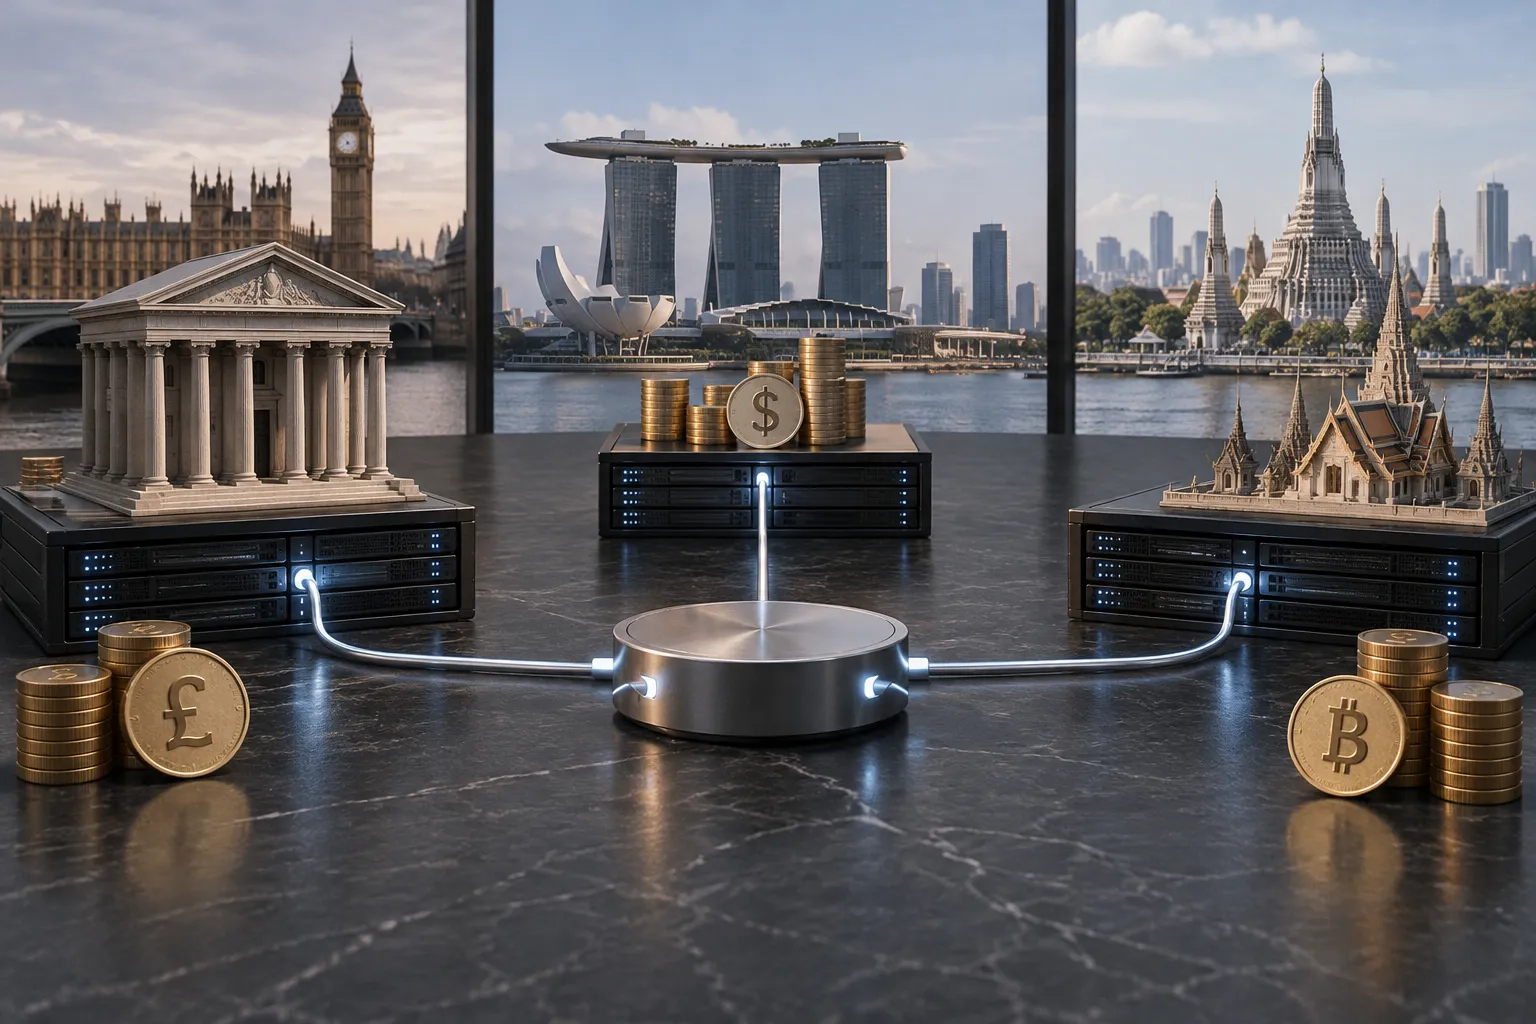
The Bank of England, Monetary Authority of Singapore and Bank of Thailand have completed Project Meridian FX APAC, a trial showing that foreign-exchange payments can be synchronised across separate simulated RTGS and distributed-ledger systems without moving them onto a unified ledger. A Synchronisation Operator prototype built by Partior coordinated payment matching, funds reservation, exception handling and atomic execution across three distinct environments.
The result addresses a settlement-risk problem: the project cited BIS data showing that more than $1.4 trillion in average daily FX turnover remained settled bilaterally without payment-versus-payment protection in April 2025. But the technical result is not a blueprint for immediate deployment. Singapore’s test environment lacked native funds reservation, requiring an escrow workaround that temporarily put the operator in custody of funds. The central banks also distinguished atomic execution from legal settlement finality and flagged the regulatory consequences of escrow or netting. The Bank of England plans a live RTGS synchronisation interface in 2028.
The Bank of England, Monetary Authority of Singapore (MAS) and Bank of Thailand have completed a trial showing that foreign-exchange payments can be settled together across separate simulated real-time gross settlement (RTGS) and distributed-ledger systems, without putting every participating currency on a unified ledger.
Their Project Meridian FX APAC reports describe an external Synchronisation Operator that coordinated payments across three different test environments. The trial demonstrated atomic payment-versus-payment (PvP) settlement: either both sides of an FX exchange execute, or neither does. It also tested multilateral net settlement across the separate systems. The findings offer a technical route to reducing FX settlement risk, while exposing legal and operational questions that a live service would have to resolve.
Three architectures, one coordinated transaction
The project connected simulations representing three different approaches to central bank money. The Bank of England used its Synchronisation Lab RTGS simulation. The Bank of Thailand used its tokenised Project SAN platform with an interoperability layer. MAS used its SGD Testnet, a wholesale central bank digital currency shared ledger.
Partior built and tested the Synchronisation Operator prototype. It coordinated funds reservation, payment matching, exception handling and atomic execution across the environments. Rather than requiring the systems to share one ledger, the operator linked the steps needed to complete a transaction on each system.
That distinction matters because RTGS systems and distributed ledgers do not necessarily provide identical functions. A common coordination process can connect them, but its design depends on what each participating system can do. The trial established that synchronised execution is technically possible in these simulations; it did not establish that every existing system can support the same process without changes.
The central banks published an executive summary and introduction alongside technical and policy reports on 13 November 2026. The Reserve Bank of Australia and Bangko Sentral ng Pilipinas participated as observer central banks and contributed to the policy and legal assessment.
Why payment-versus-payment matters
In an FX transaction, PvP links the delivery of the two currencies so that one payment does not complete without the other. Without that protection, a counterparty can pay out one currency while remaining exposed to whether it receives the other.
The project cited the 2025 Bank for International Settlements Triennial Survey, which showed that more than $1.4 trillion in average daily global FX turnover in April 2025—roughly 10% of the total—remained settled on a gross bilateral basis without PvP protection. The figure explains the project's focus on coordinating payments across systems that are not already operating on a single platform.
The trial's result is therefore narrower than a claim that FX settlement risk has been removed. It showed that a prototype could coordinate atomic settlement and multilateral net settlement in controlled environments. Whether the approach can provide equivalent protection in production depends on the participating systems, their rules and the operator's responsibilities.
Escrow exposed a design constraint
One of the clearest limitations emerged in Singapore's test environment. The SGD Testnet did not support native funds reservation, so the Synchronisation Operator used a dedicated escrow account to hold funds temporarily. That meant the operator took custody of funds in this part of the experiment. The central banks described escrow as an experimental workaround, not the intended non-custodial target model.
The difference has regulatory consequences. An operator that only coordinates non-custodial earmarking of funds has a different role from one that holds money or calculates netting obligations. The central banks warned that escrow and netting functions could shift the operator's regulatory profile towards custodial or clearing activities.
The policy report also separates technical atomicity from legal settlement finality. An all-or-nothing technical process does not, by itself, determine when a payment becomes legally final. That requires clear provisions in participating systems' rulebooks, relevant statutory finality protections and alignment across jurisdictions. The report discusses these questions in relation to Principle 8 of the CPMI-IOSCO Principles for Financial Market Infrastructures.
From trial to live interface
The Bank of England plans to launch a live synchronisation interface for its RTGS system in 2028 and expects insights from Project Meridian FX APAC to inform its implementation. The trial provides evidence that heterogeneous systems can coordinate settlement without a unified ledger. Its escrow workaround and policy findings show why technical interoperability alone is not enough to define a deployable cross-border settlement service.
The Bank of England, Monetary Authority of Singapore and Bank of Thailand have completed Project Meridian FX APAC, a trial showing that foreign-exchange payments can be synchronised across separate simulated RTGS and distributed-ledger systems without moving them onto a unified ledger. A Synchronisation Operator prototype built by Partior coordinated payment matching, funds reservation, exception handling and atomic execution across three distinct environments. The result addresses a settlement-risk problem: the project cited BIS data showing that more than $1.4 trillion in average daily FX turnover remained settled bilaterally without payment-versus-payment protection in April 2025. But the technical result is not a blueprint for immediate deployment. Singapore’s test environment lacked native funds reservation, requiring an escrow workaround that temporarily put the operator in custody of funds. The central banks also distinguished atomic execution from legal settlement finality and flagged the regulatory consequences of escrow or netting. The Bank of England plans a live RTGS synchronisation interface in 2028.
The Bank of England, Monetary Authority of Singapore and Bank of Thailand have published results from Project Meridian FX APAC, a test of synchronized foreign-exchange settlement across three different types of payment system. Partior built the prototype Synchronisation Operator, which coordinated conditional payments without requiring the participating systems to share a single ledger. The test demonstrated bilateral payment-versus-payment settlement and multilateral netting, including safeguards against partial execution during simulated failures. The findings are limited to test environments: no live transactions or real reserves were settled. The banks’ policy report also warns that coordinating payment instructions does not, by itself, establish legal settlement finality across borders. The Bank of England plans a live synchronization interface for its RTGS system by 2028, while the Singaporean and Thai authorities have made no domestic implementation commitment. Further legal and oversight arrangements would be needed for a live cross-border service.
Payments Canada launched the Real-Time Rail on November 9, 2026, establishing a system for round-the-clock clearing and settlement. Its eight initial participants include Wealthsimple, KOHO, Questbank and Bank of America, but none of Canada’s Big Six banks. Because both institutions in a payment must participate, the launch does not yet bring instant transfers to most Canadian bank accounts. Wealthsimple says it is testing the system and plans to offer cross-institutional instant payments to retail and business clients in 2027. The rail has an initial $100,000 transaction limit, uses ISO 20022 messaging and requires centralized fraud controls. It is also subject to Bank of Canada oversight as a prominent payment system. Payments Canada aims to connect more than nine in ten Canadian bank accounts by the third quarter of 2027, as major banks complete their integrations. Existing Interac e-Transfer traffic is scheduled to begin moving onto the rail in early 2027.
Synctera announced a $24.5 million growth financing round on November 6, 2026, bringing its total funding to $126.7 million. The banking-as-a-service provider also added Main Street Bank as its eighth active sponsor bank partner and disclosed that two more banks were in final implementation stages. Synctera said the funding is intended to provide runway until it reaches profitability, rather than support aggressive hiring. Alongside the financing, Synctera registered as a Money Services Business with FinCEN, established its own anti-money laundering program and took on suspicious activity and currency transaction reporting obligations. Those changes come as banks face closer scrutiny of fintech programs and custodial account records following the 2024 bankruptcy of Synapse Financial Technologies. Synctera says its multi-bank network reduces dependence on any one sponsor bank, but individual banks remain responsible for their own compliance and custodial records.
Swift has deferred payments-related changes in its Standards Release 2026, including a rule that would have rejected cross-border payment messages containing unstructured postal addresses from 14 November 2026. The decision, announced on 27 August, followed evidence that existing payment data was not ready: network figures presented at Sibos showed that 51% of debtor addresses and 53% of creditor addresses remained unstructured. More than 60% of live payment traffic would have faced rejection under the planned rule. The delay does not apply uniformly to every payment system. Four Asia-Pacific domestic infrastructures retained their November 2026 deadlines, while the European Payments Council removed a corresponding cut-off from its SEPA scheme rules. J.P. Morgan says cross-border payment changes have moved to Standards Release 2027 or later, allowing unstructured addresses until at least November 2027. The underlying challenge remains: banks must improve customer address data, not just change the format of payment messages.
PhotonPay has closed a $40 million Series C round led by Blockchain Capital to expand its stablecoin-focused Financial OS. SBI Group joined as a new investor, alongside existing backers IDG Capital, GL Ventures and Lightspeed Faction. The funding follows a January 2026 Series B round. PhotonPay reported $65 billion in annualized transaction volume as of August 2026, up from $30 billion reported at the time of its Series B. Its model combines stablecoin liquidity with bank relationships and local payment networks, rather than replacing those networks outright. The company says it holds 34 payment and financial licenses and regulatory authorizations and serves more than 200,000 corporate clients. It also plans an execution layer supporting the Model Context Protocol for autonomous AI agents. The expansion comes as Stripe and specialist firms including Rain and MassPay pursue corporate settlement opportunities.