Synctera Raises $24.5 Million, Adds Eighth Sponsor Bank and Takes On AML Duties
Nov. 9, 2026 • Article • Banking & Payments
Synctera announced a $24.5 million growth financing round on November 6, 2026, bringing its total funding to $126.7 million. The banking-as-a-service provider also added Main Street Bank as its eighth active sponsor bank partner and disclosed that two more banks were in final implementation stages. Synctera said the funding is intended to provide runway until it reaches profitability, rather than support aggressive hiring.
Alongside the financing, Synctera registered as a Money Services Business with FinCEN, established its own anti-money laundering program and took on suspicious activity and currency transaction reporting obligations. Those changes come as banks face closer scrutiny of fintech programs and custodial account records following the 2024 bankruptcy of Synapse Financial Technologies. Synctera says its multi-bank network reduces dependence on any one sponsor bank, but individual banks remain responsible for their own compliance and custodial records.
Synctera announced a $24.5 million growth financing round on November 6, 2026, as it expanded its sponsor-bank network and assumed additional anti-money laundering responsibilities. The banking-as-a-service (BaaS) infrastructure provider said the round brings its cumulative funding to $126.7 million. It also disclosed that Main Street Bank had become its eighth active sponsor bank partner.
The developments put bank oversight at the center of Synctera’s expansion. Fintech companies use BaaS infrastructure to offer financial products through licensed banks, making reliable records and clear compliance responsibilities important to both sides. Synctera said the new capital is intended to provide operating runway until it reaches profitability and break-even status, rather than fund aggressive headcount growth.
Funding supports a broader bank network
The financing included Multiplier Capital, Fin Capital, 1st & Main Growth Partners, Diagram and NAventures, the venture capital subsidiary of National Bank of Canada. Synctera said two further banks were in the final stages of implementation and scheduled to launch programs in the fourth quarter of 2026.
Synctera reported signing 20 new enterprise and fintech clients during 2026 across property management, small-business lending and financial services. It also reported that gross merchandise value and interchange revenue had each doubled year over year. Those are company-reported measures of activity, not a disclosure that Synctera has reached profitability.
Main Street Bank, based in Massachusetts, is the latest active addition to a model built around multiple sponsor banks. Its chief executive, Walter J. Dwyer IV, said the bank selected Synctera for direct visibility into program-level compliance and an approach aligned with bank regulatory expectations. Multiplier Capital Managing Director Ash Vaidya has argued that banks need independent sub-ledgers, automated reconciliation and continuous control monitoring before re-entering BaaS programs.
Synctera assumes direct reporting duties
Alongside the funding announcement, Synctera disclosed that it had registered with the Financial Crimes Enforcement Network, or FinCEN, as a Money Services Business. The company established its own anti-money laundering program and directly assumed suspicious activity reporting and currency transaction reporting obligations.
That step gives Synctera defined reporting duties of its own; it does not make the company the custodian of customers’ money. Synctera general counsel Conway Ekpo said consumer funds remain in for-the-benefit-of, or FBO, accounts at partner banks, rather than being held by Synctera.
The company has also invested in compliance technology. It acquired regulatory technology firm Cable in April 2026 to embed automated, continuous control testing across fintech programs instead of relying on periodic manual sampling. The acquisition and MSB registration address different parts of program oversight: one concerns ongoing tests of controls, while the other establishes Synctera’s own anti-money laundering and reporting responsibilities.
Ledger controls remain a bank-level concern
Synctera operates a sub-ledger that tracks client accounts against corresponding FBO or general ledger accounts at partner banks. It produces nightly reconciliation batch files to check sub-ledger balances against bank core balances every business day. Reconciliation is the process of checking that transaction and account records agree; discrepancies can make it difficult to determine how much money belongs to each customer.
That distinction became especially consequential after the 2024 bankruptcy of BaaS middleware provider Synapse Financial Technologies. The bankruptcy left tens of millions of dollars in end-user funds frozen amid unreconciled ledger discrepancies across multiple partner banks. The episode sharpened attention on which institutions hold customer funds and whether banks can verify the records behind custodial accounts.
In 2024, the Federal Deposit Insurance Corporation proposed custodial deposit recordkeeping requirements for banks’ third-party accounts. The proposal called for banks to maintain direct records of beneficial owners and conduct daily sub-ledger reconciliations for FBO custodial accounts. It was a proposal, not an indication that those requirements had taken effect.
Synctera and its investors argue that access to multiple sponsor banks can reduce reliance on any single banking partner, so a change at one bank need not stop every client program. That claim has a limit: a multi-bank arrangement also creates more relationships and records to manage. Regulatory and legal analyses cited in the research package say individual partner banks retain compliance obligations and responsibility for custodial ledgers; working through middleware does not transfer those duties away.
Next launches will test the model
Synctera introduced Synctera Labs in October 2026 as a packaged launchpad for early-stage embedded-finance programs, with initial programs scheduled to go live in February 2027. Together with the two bank implementations slated for the fourth quarter of 2026, those launches are the next stated steps in its expansion.
The financing gives Synctera runway to pursue those plans while it works toward profitability. The operational test is whether its growing network can preserve bank-level visibility, accurate daily records and clear reporting responsibilities as more programs come online.
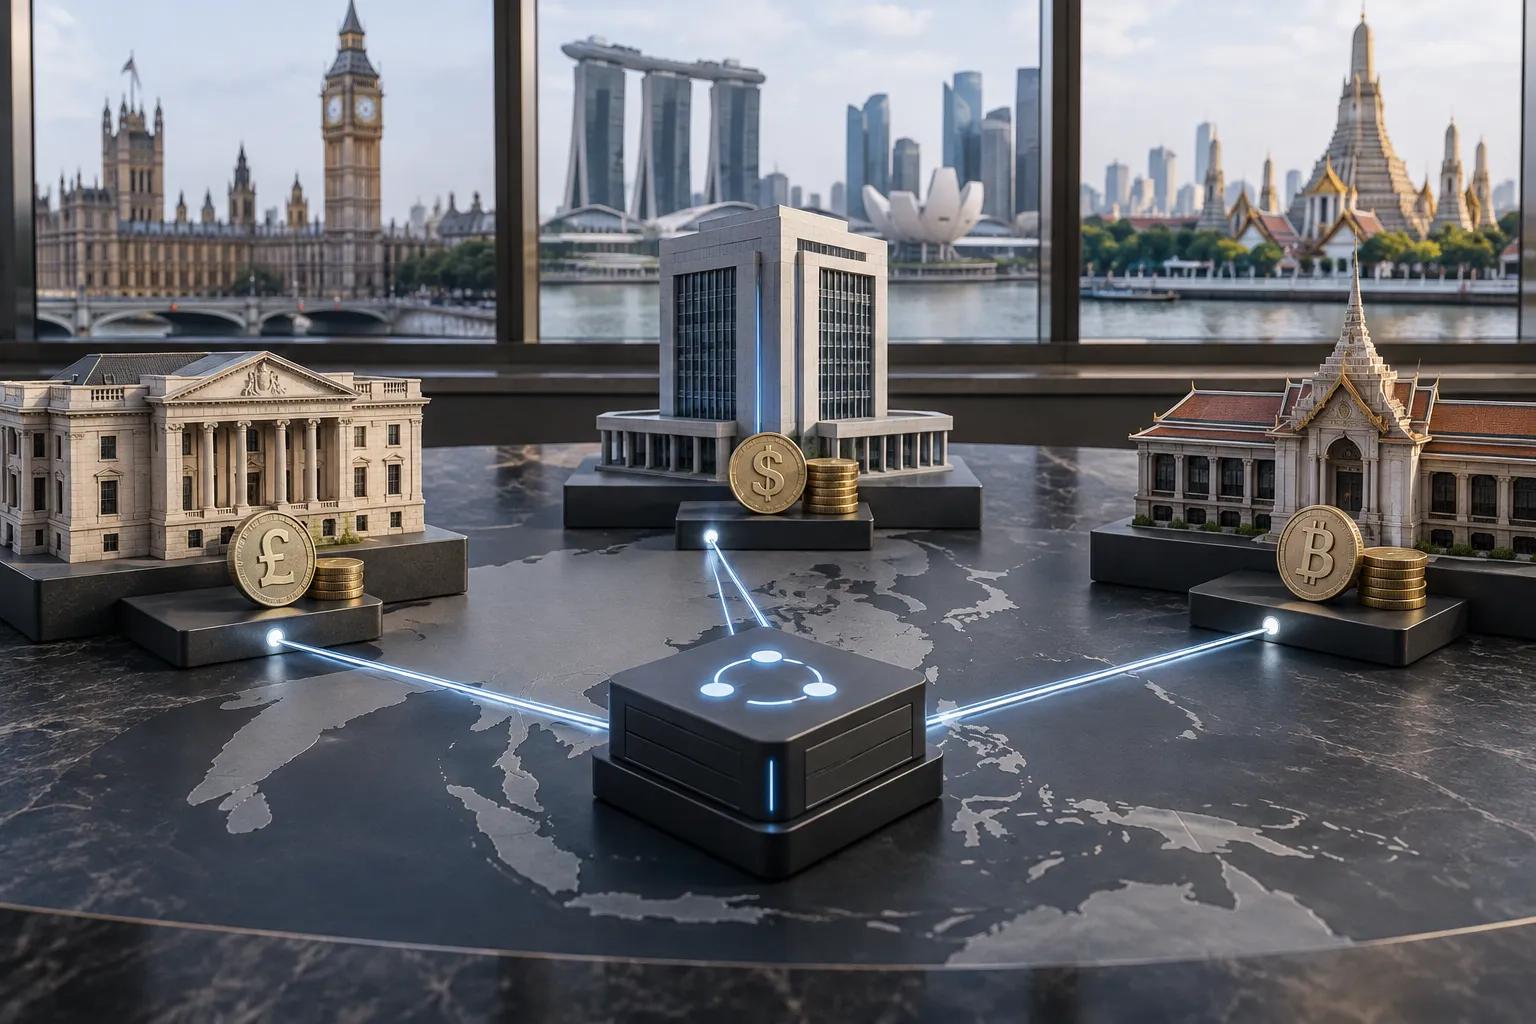
The Bank of England, Monetary Authority of Singapore and Bank of Thailand have published results from Project Meridian FX APAC, a test of synchronized foreign-exchange settlement across three different types of payment system. Partior built the prototype Synchronisation Operator, which coordinated conditional payments without requiring the participating systems to share a single ledger. The test demonstrated bilateral payment-versus-payment settlement and multilateral netting, including safeguards against partial execution during simulated failures. The findings are limited to test environments: no live transactions or real reserves were settled. The banks’ policy report also warns that coordinating payment instructions does not, by itself, establish legal settlement finality across borders. The Bank of England plans a live synchronization interface for its RTGS system by 2028, while the Singaporean and Thai authorities have made no domestic implementation commitment. Further legal and oversight arrangements would be needed for a live cross-border service.
Payments Canada launched the Real-Time Rail on November 9, 2026, establishing a system for round-the-clock clearing and settlement. Its eight initial participants include Wealthsimple, KOHO, Questbank and Bank of America, but none of Canada’s Big Six banks. Because both institutions in a payment must participate, the launch does not yet bring instant transfers to most Canadian bank accounts. Wealthsimple says it is testing the system and plans to offer cross-institutional instant payments to retail and business clients in 2027. The rail has an initial $100,000 transaction limit, uses ISO 20022 messaging and requires centralized fraud controls. It is also subject to Bank of Canada oversight as a prominent payment system. Payments Canada aims to connect more than nine in ten Canadian bank accounts by the third quarter of 2027, as major banks complete their integrations. Existing Interac e-Transfer traffic is scheduled to begin moving onto the rail in early 2027.
Synctera announced a $24.5 million growth financing round on November 6, 2026, bringing its total funding to $126.7 million. The banking-as-a-service provider also added Main Street Bank as its eighth active sponsor bank partner and disclosed that two more banks were in final implementation stages. Synctera said the funding is intended to provide runway until it reaches profitability, rather than support aggressive hiring. Alongside the financing, Synctera registered as a Money Services Business with FinCEN, established its own anti-money laundering program and took on suspicious activity and currency transaction reporting obligations. Those changes come as banks face closer scrutiny of fintech programs and custodial account records following the 2024 bankruptcy of Synapse Financial Technologies. Synctera says its multi-bank network reduces dependence on any one sponsor bank, but individual banks remain responsible for their own compliance and custodial records.
Swift has deferred payments-related changes in its Standards Release 2026, including a rule that would have rejected cross-border payment messages containing unstructured postal addresses from 14 November 2026. The decision, announced on 27 August, followed evidence that existing payment data was not ready: network figures presented at Sibos showed that 51% of debtor addresses and 53% of creditor addresses remained unstructured. More than 60% of live payment traffic would have faced rejection under the planned rule. The delay does not apply uniformly to every payment system. Four Asia-Pacific domestic infrastructures retained their November 2026 deadlines, while the European Payments Council removed a corresponding cut-off from its SEPA scheme rules. J.P. Morgan says cross-border payment changes have moved to Standards Release 2027 or later, allowing unstructured addresses until at least November 2027. The underlying challenge remains: banks must improve customer address data, not just change the format of payment messages.
PhotonPay has closed a $40 million Series C round led by Blockchain Capital to expand its stablecoin-focused Financial OS. SBI Group joined as a new investor, alongside existing backers IDG Capital, GL Ventures and Lightspeed Faction. The funding follows a January 2026 Series B round. PhotonPay reported $65 billion in annualized transaction volume as of August 2026, up from $30 billion reported at the time of its Series B. Its model combines stablecoin liquidity with bank relationships and local payment networks, rather than replacing those networks outright. The company says it holds 34 payment and financial licenses and regulatory authorizations and serves more than 200,000 corporate clients. It also plans an execution layer supporting the Model Context Protocol for autonomous AI agents. The expansion comes as Stripe and specialist firms including Rain and MassPay pursue corporate settlement opportunities.
CRB Group, the parent of Cross River Bank, has agreed to acquire Accrue, a provider of branded wallets, stored-value infrastructure and customer loyalty software. The deal would bring technology already connected to the bank into its embedded finance business. Financial terms were not disclosed, and the transaction remained subject to customary closing conditions as of late October 2026. Cross River was already Accrue’s partner bank, holding Accrue Balance funds as an FDIC-insured depository and issuing linked Visa debit cards. Accrue’s software includes merchant-specific stored-value ledgers and a way to route merchandise refunds into store credit rather than back to an outside card issuer. Founder and CEO Michael Hershfield is set to lead Cross River’s embedded finance suite, while Accrue’s 26 staff members are expected to join Cross River’s workforce. The acquisition would move the two companies from a banking partnership to a shared operating structure, if completed.