Swift Delays ISO 20022 Address Mandate as Unstructured Data Threatens Cross-Border Payments
Nov. 7, 2026 • Deep Dive • Banking & Payments
Swift has deferred payments-related changes in its Standards Release 2026, including a rule that would have rejected cross-border payment messages containing unstructured postal addresses from 14 November 2026. The decision, announced on 27 August, followed evidence that existing payment data was not ready: network figures presented at Sibos showed that 51% of debtor addresses and 53% of creditor addresses remained unstructured. More than 60% of live payment traffic would have faced rejection under the planned rule.
The delay does not apply uniformly to every payment system. Four Asia-Pacific domestic infrastructures retained their November 2026 deadlines, while the European Payments Council removed a corresponding cut-off from its SEPA scheme rules. J.P. Morgan says cross-border payment changes have moved to Standards Release 2027 or later, allowing unstructured addresses until at least November 2027. The underlying challenge remains: banks must improve customer address data, not just change the format of payment messages.
Swift has deferred a planned rule that would have rejected cross-border payment messages containing unstructured postal addresses from 14 November 2026. Announced on 27 August, the change moves payments-related requirements out of Standards Release 2026 and gives banks more time to improve the address data they send through ISO 20022 messages.
The risk of enforcing the rule was substantial. Swift network figures presented by executives at Sibos 2026 showed that 51% of debtor addresses and 53% of creditor addresses remained unstructured. According to reporting on those figures, more than 60% of live payment traffic would have faced network rejection if the November deadline had taken effect.
The postponement concerns a specific data-quality requirement within the wider messaging transition, not a reversal of ISO 20022 adoption. J.P. Morgan’s October client guidance says cross-border payment changes covering MT Category 1, ISO 20022 CBPR+, SCORE+ and SwiftGo messages have been decoupled from Standards Release 2026 and deferred to Standards Release 2027 or later. Its guidance indicates that market participants can continue using unstructured postal addresses until at least November 2027.
Why postal addresses became a migration obstacle
ISO 20022 CBPR+ specifications already allow a transitional “hybrid” address. Rather than requiring every part of an address to be entered separately, the format places Town Name and Country Code in structured fields while permitting up to two free-text address lines of 70 characters each. Those fields help systems identify basic location information without demanding a completely structured address from the outset.
Even that limited requirement has proved difficult where customer information sits in legacy core banking or enterprise resource planning databases. According to the research presented, those records do not always separate a town and country reliably from the rest of an address. Changing the payment message alone therefore cannot guarantee that a bank has the information needed to populate the required fields.
A RedCompass Labs survey of banks in North America and Europe found that 44% were behind schedule on the structured-address transition. Among banks with assets exceeding $250 billion, 20% considered the original November 2026 deadline unrealistic, compared with 5% of smaller institutions in the survey. The findings point to a data remediation problem extending beyond the technical work of updating messaging systems.
The distinction matters for operations and compliance. Payments with incomplete or poorly formatted addresses can require investigation or manual repair, or be rejected by a clearing system. Industry benchmarking cited in the research puts the operational cost of such failures at $25 to $50 per transaction for correspondent banks. Payments compliance executives have also warned that poorly parsed free text can produce false positives in automated sanctions screening and transaction monitoring.
A revised timetable, but not a universal reprieve
The consequences of Swift’s decision differ across systems. On the day Swift announced its deferral, the Bank of England postponed its November 2026 RTGS and CHAPS messaging standards release in its entirety. The European Payments Council subsequently updated its address-formatting guidance and five 2025 SEPA payment scheme rulebooks, removing a 15 November 2026 cut-off that would have barred unstructured postal addresses.
Four Asia-Pacific domestic market infrastructures took a different course. BOK-Wire+ in South Korea, PhilPaSSplus in the Philippines, FISC in Taiwan and CIPS in China retained their November 2026 deadlines for removing fully unstructured postal addresses. Banks therefore cannot treat the Swift cross-border deferral as a blanket change to every domestic high-value payment requirement.
The remaining Standards Release 2026 work also has a separate schedule. Clearstream told market participants that Swift had set 12 June 2027 for non-payment components, including MT messages outside Category 1, securities, funds, tracker and investigations. It said the scope of Standards Release 2027 was due to be finalized in December 2026, leaving the eventual cross-border payment address mandate uncommitted at the time of its notice.
What banks still need to resolve
The extra time reduces the immediate prospect of widespread message rejection, but it does not remove the need to clean up address records. Institutions processing cross-border payments must still determine whether their source systems can consistently identify the town and country required by the hybrid format and pass that information through to payment messages.
The experience also illustrates the difference between adopting an ISO 20022 message and making the underlying customer data usable. Swift’s revised timetable addresses a near-term network risk; the ability to meet a future address mandate depends on correcting the records from which those messages are built.
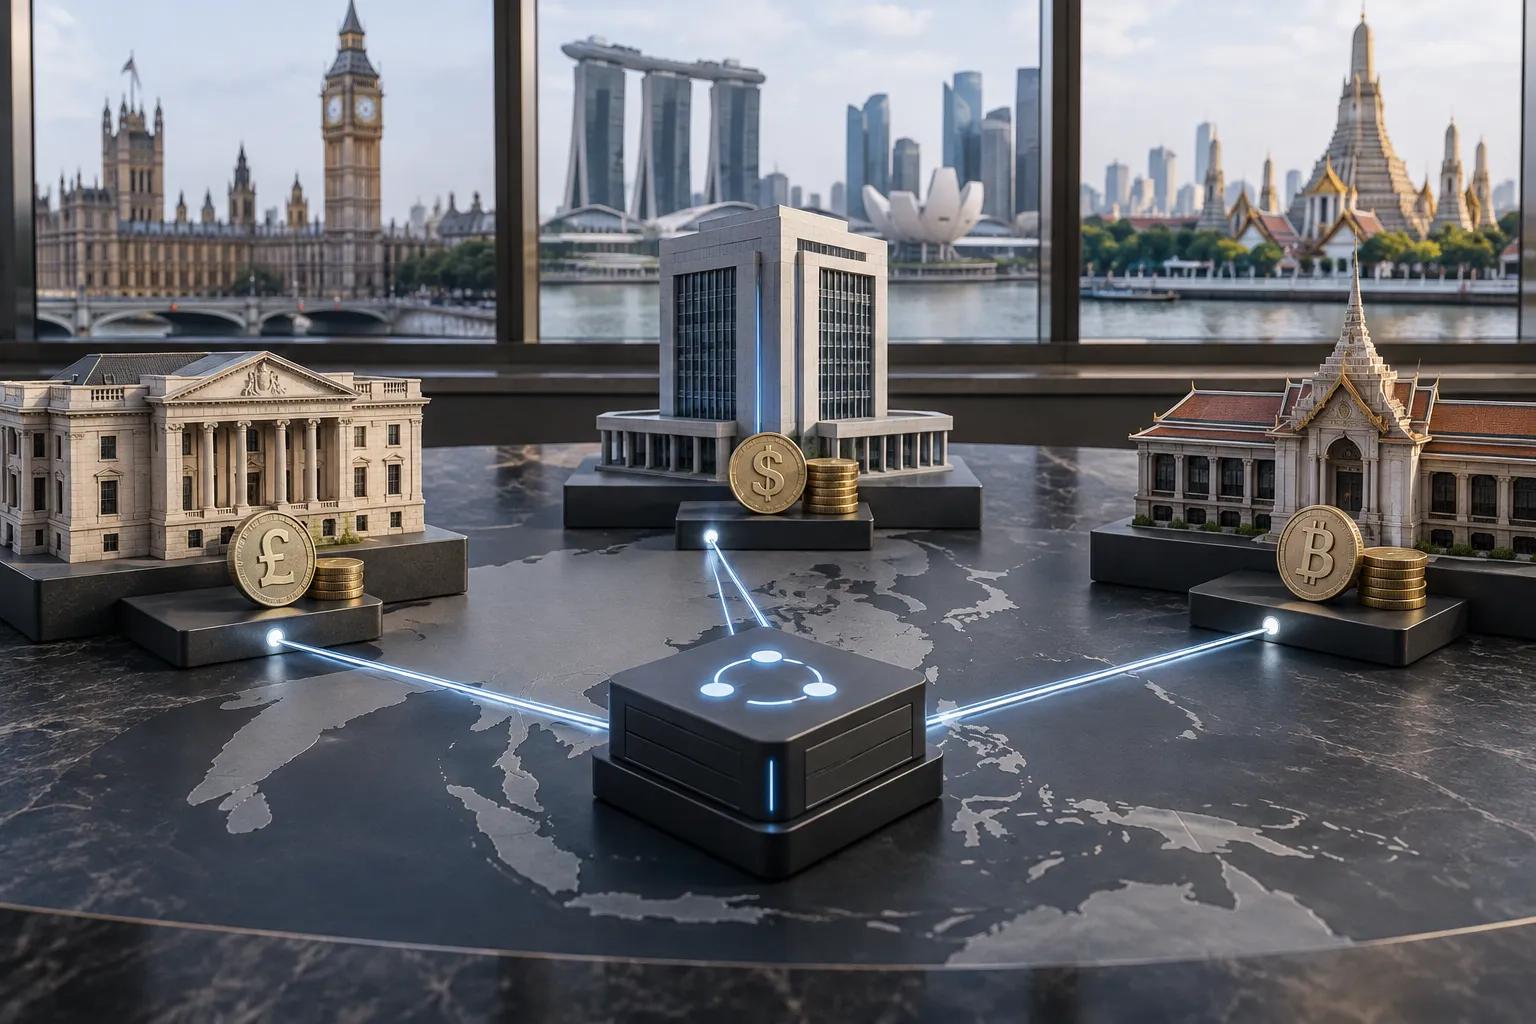
The Bank of England, Monetary Authority of Singapore and Bank of Thailand have published results from Project Meridian FX APAC, a test of synchronized foreign-exchange settlement across three different types of payment system. Partior built the prototype Synchronisation Operator, which coordinated conditional payments without requiring the participating systems to share a single ledger. The test demonstrated bilateral payment-versus-payment settlement and multilateral netting, including safeguards against partial execution during simulated failures. The findings are limited to test environments: no live transactions or real reserves were settled. The banks’ policy report also warns that coordinating payment instructions does not, by itself, establish legal settlement finality across borders. The Bank of England plans a live synchronization interface for its RTGS system by 2028, while the Singaporean and Thai authorities have made no domestic implementation commitment. Further legal and oversight arrangements would be needed for a live cross-border service.
Payments Canada launched the Real-Time Rail on November 9, 2026, establishing a system for round-the-clock clearing and settlement. Its eight initial participants include Wealthsimple, KOHO, Questbank and Bank of America, but none of Canada’s Big Six banks. Because both institutions in a payment must participate, the launch does not yet bring instant transfers to most Canadian bank accounts. Wealthsimple says it is testing the system and plans to offer cross-institutional instant payments to retail and business clients in 2027. The rail has an initial $100,000 transaction limit, uses ISO 20022 messaging and requires centralized fraud controls. It is also subject to Bank of Canada oversight as a prominent payment system. Payments Canada aims to connect more than nine in ten Canadian bank accounts by the third quarter of 2027, as major banks complete their integrations. Existing Interac e-Transfer traffic is scheduled to begin moving onto the rail in early 2027.
Synctera announced a $24.5 million growth financing round on November 6, 2026, bringing its total funding to $126.7 million. The banking-as-a-service provider also added Main Street Bank as its eighth active sponsor bank partner and disclosed that two more banks were in final implementation stages. Synctera said the funding is intended to provide runway until it reaches profitability, rather than support aggressive hiring. Alongside the financing, Synctera registered as a Money Services Business with FinCEN, established its own anti-money laundering program and took on suspicious activity and currency transaction reporting obligations. Those changes come as banks face closer scrutiny of fintech programs and custodial account records following the 2024 bankruptcy of Synapse Financial Technologies. Synctera says its multi-bank network reduces dependence on any one sponsor bank, but individual banks remain responsible for their own compliance and custodial records.
Swift has deferred payments-related changes in its Standards Release 2026, including a rule that would have rejected cross-border payment messages containing unstructured postal addresses from 14 November 2026. The decision, announced on 27 August, followed evidence that existing payment data was not ready: network figures presented at Sibos showed that 51% of debtor addresses and 53% of creditor addresses remained unstructured. More than 60% of live payment traffic would have faced rejection under the planned rule. The delay does not apply uniformly to every payment system. Four Asia-Pacific domestic infrastructures retained their November 2026 deadlines, while the European Payments Council removed a corresponding cut-off from its SEPA scheme rules. J.P. Morgan says cross-border payment changes have moved to Standards Release 2027 or later, allowing unstructured addresses until at least November 2027. The underlying challenge remains: banks must improve customer address data, not just change the format of payment messages.
PhotonPay has closed a $40 million Series C round led by Blockchain Capital to expand its stablecoin-focused Financial OS. SBI Group joined as a new investor, alongside existing backers IDG Capital, GL Ventures and Lightspeed Faction. The funding follows a January 2026 Series B round. PhotonPay reported $65 billion in annualized transaction volume as of August 2026, up from $30 billion reported at the time of its Series B. Its model combines stablecoin liquidity with bank relationships and local payment networks, rather than replacing those networks outright. The company says it holds 34 payment and financial licenses and regulatory authorizations and serves more than 200,000 corporate clients. It also plans an execution layer supporting the Model Context Protocol for autonomous AI agents. The expansion comes as Stripe and specialist firms including Rain and MassPay pursue corporate settlement opportunities.
CRB Group, the parent of Cross River Bank, has agreed to acquire Accrue, a provider of branded wallets, stored-value infrastructure and customer loyalty software. The deal would bring technology already connected to the bank into its embedded finance business. Financial terms were not disclosed, and the transaction remained subject to customary closing conditions as of late October 2026. Cross River was already Accrue’s partner bank, holding Accrue Balance funds as an FDIC-insured depository and issuing linked Visa debit cards. Accrue’s software includes merchant-specific stored-value ledgers and a way to route merchandise refunds into store credit rather than back to an outside card issuer. Founder and CEO Michael Hershfield is set to lead Cross River’s embedded finance suite, while Accrue’s 26 staff members are expected to join Cross River’s workforce. The acquisition would move the two companies from a banking partnership to a shared operating structure, if completed.